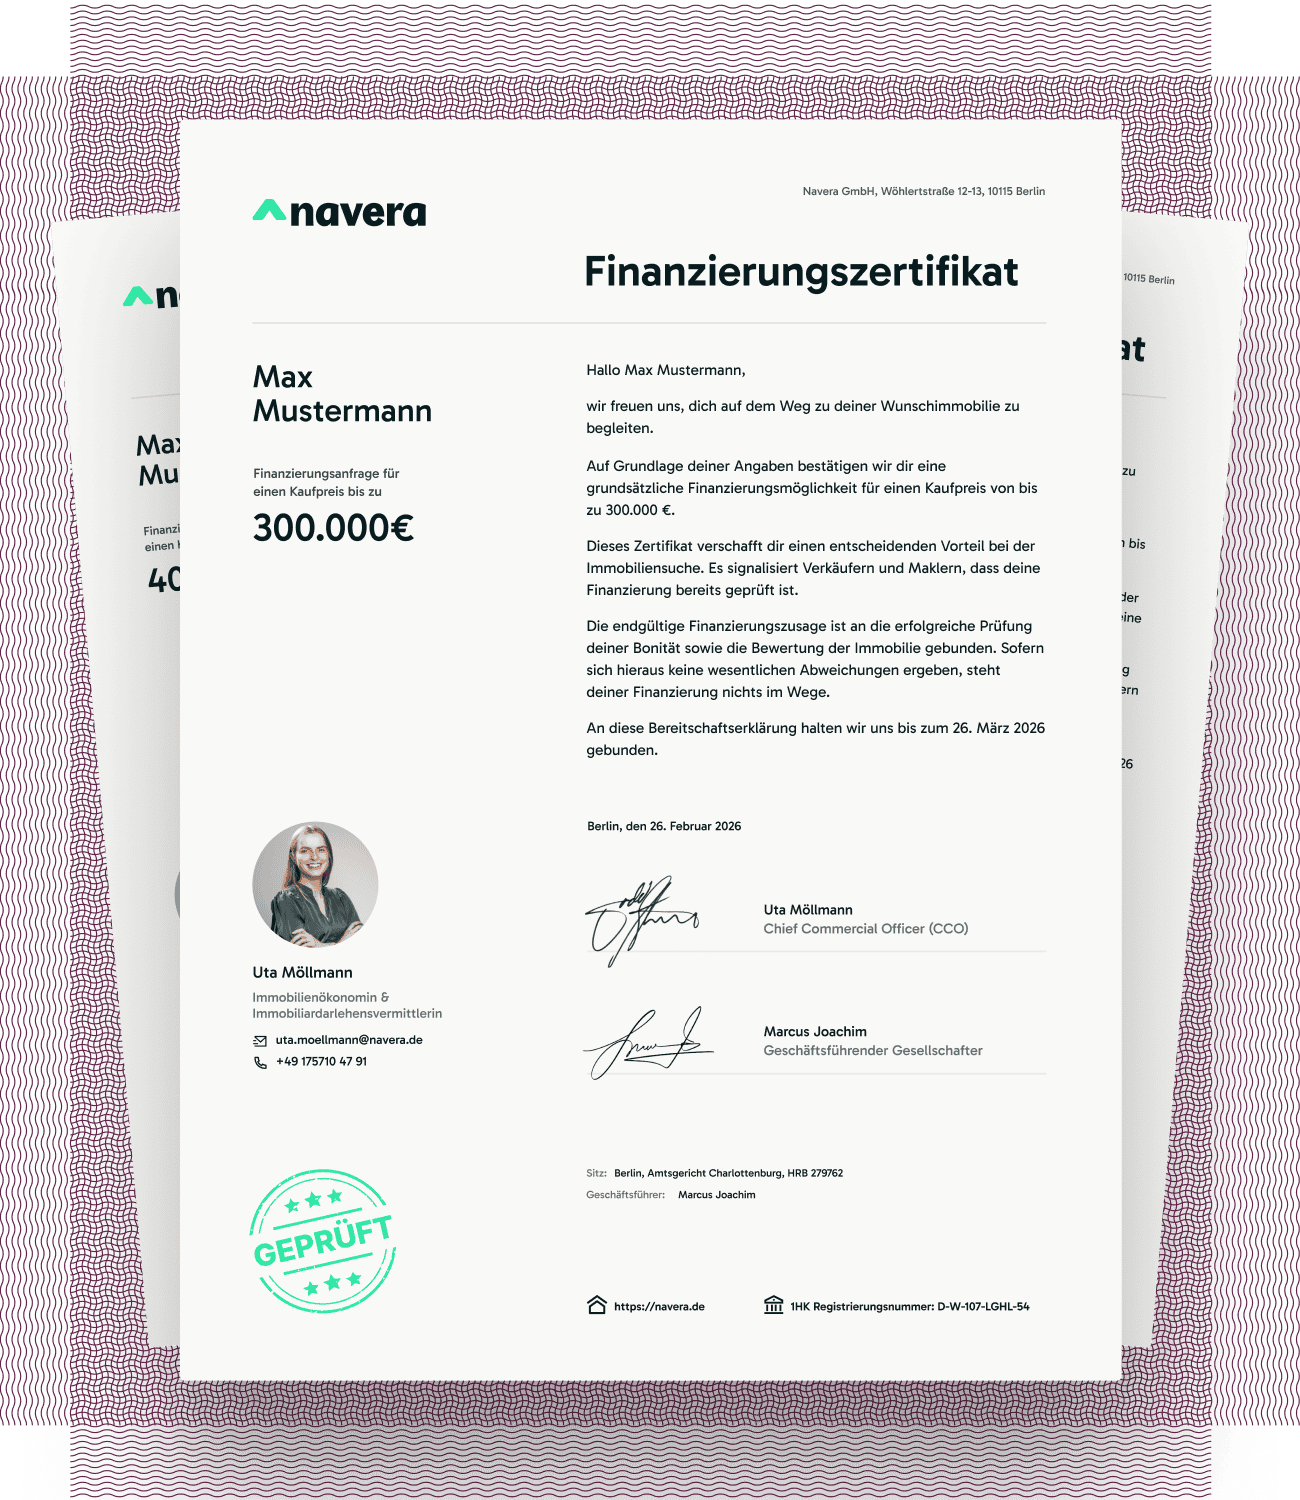
Financing certificate: how to strengthen your buying position.
You've found the apartment. The location is right, the floor plan works, the price is within range. You call the broker to arrange a viewing, and they immediately ask you: "Do you already have a financing certificate or a financing confirmation?" Anyone who hesitates here loses out. Not because the broker is being rude, but because that's how the housing market in Germany works: sellers choose the buyer who brings the most certainty. A financing certificate, often also called a mortgage financing certificate, is a document that confirms you are in principle able to finance a property up to a certain amount. It is not a loan agreement, but it opens doors that stay closed without this proof of creditworthiness for real estate. The good news: today you can apply for this proof free of charge and without any impact on your Schufa score, in just a few minutes online. This article explains what the certificate really means, which documents you need, how binding it is and how to obtain it quickly and correctly.
What a financing certificate really means.
The term often causes confusion because it is not used consistently in everyday life. Some banks talk about a "financing confirmation", others about a "financing pass" or "mortgage financing certificate". At its core, the same thing lies behind all of these: an initial, non-binding assessment of your ability to pay, based on a rough review of your income and your own funds. What's important: the certificate refers to a maximum purchase-price range, not to a specific property. So you apply for it during the property search, long before you have found a particular house or apartment, which is what makes it so practical.
Financing certificate vs. financing confirmation: where's the real difference?
The two terms are often used synonymously, but they describe different depths of review. The certificate is an initial estimate: the bank or advisor briefly looks at your income and equity and issues you a document subject to a final review. The binding financing confirmation only comes after a detailed creditworthiness and property review, in which the bank also evaluates the specific property. You obtain the binding confirmation shortly before signing the purchase contract. Only the signed loan agreement creates real legal certainty for both sides. Knowing this sequence protects you from expensive mistakes. You use the certificate for the property search and initial viewings. You obtain the binding confirmation when it comes to a very specific property.
Why the certificate increases your chances on the housing market.
In practice it looks like this: when two interested parties make the same offer for an apartment side by side, same purchase price, similar creditworthiness, the decision almost always goes in favour of the one who can present a preliminary financing commitment. Brokers consistently report that sellers almost always prefer the buyer whose financing seems secured. Not out of malice, but because the seller doesn't want to take the risk of waiting for a buyer whose financing ends up falling through. Brokers proactively ask for proof of creditworthiness, often even before the first viewing. In sought-after locations this has long been standard. Anyone who already has the confirmation in their pocket signals: I'm not just a searcher who doesn't yet know whether they can afford it. I'm a serious buyer who is prepared.
Without a certificate: what you concretely risk.
Anyone who only applies for a certificate or even a preliminary financing confirmation after the viewing loses valuable days. In a competitive market a property can be allocated within 24 to 48 hours. On top of that: without proof, your negotiating position is weaker. Sellers and brokers simply don't know whether you can deliver. Especially in cities like Munich, Hamburg, Berlin or Frankfurt, where several offers land on the table at the same time, a budget confirmation decides whether you even make the shortlist. The certificate is not a bureaucratic nice-to-have, it's a real competitive instrument.
What Schufa-neutral really means.
When a provider makes a Schufa enquiry, there are two variants: the conditions enquiry and the credit enquiry. The conditions enquiry is neutral, it is recorded with Schufa, but it does not affect your score and is not visible to other banks. The hard credit enquiry, on the other hand, can worsen your Schufa score, even if you don't end up taking the loan. A Schufa-neutral financing certificate protects your score as long as the financing is not yet concrete. This is particularly important when you are comparing multiple providers or don't yet know which property it will end up being.
How legally binding is the certificate?
Here lies one of the most common misconceptions: many buyers confuse the preliminary financing commitment with a credit promise from the bank. Neither the financing confirmation nor the financing certificate is binding, it is therefore not a loan agreement and not a legally enforceable promise. It is an initial estimate, subject to reservation. That means: there can still be aspects that speak against a credit commitment, particularly when relevant factors change. Typical reasons are a job change, a loss of income, a deterioration in the property's value or incorrect information in the application. That's why it's important to keep your financial situation stable between the certificate and the purchase contract. This is particularly important when you are comparing multiple providers or don't yet know which property it will end up being.
Validity period and what you specifically need to keep in mind.
As a rule, a financing certificate is valid for 3 months. There is no statutory requirement for this, every bank determines it individually. If the certificate is tied to a specific property, it ideally should not be older than four weeks. It is advisable not to sign the purchase contract while the final financing commitment is still outstanding. Without a binding confirmation, you as the buyer are liable with all your assets if you cannot pay the purchase price. A financing reservation agreed with a notary in the purchase contract gives you protection here: it allows you to withdraw from the contract if financing is not arranged within an agreed deadline. Therefore, always have the purchase contract reviewed by a lawyer before you sign.
How to get your financing certificate in just a few steps.
The process is straightforward. You simply enter your key figures, income, equity and desired purchase-price range, into our calculator. We then check your details as part of a conditions enquiry, and you receive the certificate as a PDF by email, usually within just a few minutes. If you request the certificate from another provider, make sure the document meets the following requirements: a solid document includes your full name and address, the confirmed purchase-price range as a maximum amount, the issue date and validity period, as well as the issuer's letterhead. It should also include a note that this is a non-binding assessment subject to the final review. A typical sample text for a financing confirmation reads, for example: "Based on the information provided, we preliminarily confirm that Mr/Ms [Name] is in principle able to finance a property up to a purchase price of [amount] euros. This confirmation is subject to a complete creditworthiness and property review." More practical examples and formulations for financing confirmations are offered, among others, by Dr. Klein.
With Navera: free of charge, Schufa-neutral, ready online in minutes.
At Navera, you apply for your financing certificate free of charge and fully Schufa-neutral directly online. You enter your details on income, equity and desired purchase-price range and receive the certificate directly as a PDF, without waiting times and without stacks of paper. A difference many users appreciate: Navera advisors are paid a fixed salary, not on a commission basis. That means they recommend what really fits your situation. For questions, you can reach them in the evenings and at weekends via WhatsApp, email or video call, i.e. when you actually have time. When the search turns into a follow-up financing or a concrete financing, Navera compares more than 600 banking partners in the background and shows you not only the interest rate, but also the total cost, the residual debt and the flexibility of each offer. Navera is a good fit for employees actively searching for a property, equally for first-time buyers still finding their bearings in the market, and for everyone who has to coordinate selling and buying at the same time. For questions about usage and legal details, you can also take a look at the General Terms and Conditions.
Conclusion: a certificate is not paperwork, it's your negotiating advantage.
A preliminary financing commitment is the first concrete step from searcher to serious buyer. Anyone who goes into viewings prepared more often wins the contract. Anyone who knows the legal classification of the document makes better decisions on the purchase contract. And anyone who pulls together the documents early saves themselves stress at exactly the moment when it matters most. The most important practical tip: don't apply for the financing certificate only when you already have an apartment in your sights. Apply for it now, so that you have it in your pocket when the right property appears. Because in a fast market, it's often not the highest price that decides, but the greatest certainty. Get started now: apply for your financing certificate free of charge and Schufa-neutral with Navera and walk into your next viewing with the necessary confidence.